Monthly Report | China's Online Notebook Computer Market in August 2026: Sales Volume Drops 21%, Apple and Xiaomi Buck the Trend to Gain Market Share; Average Price Rises 12%, Share of Models Priced O
 09/28 2026
 451
According to the report
Sales Volume Drops Over 20%, Rising Average Prices Support Sales Amount
The overall market in August continued the weak trend from the first half of the year, with an expanded year-on-year decline in sales volume. However, the decline in sales did not proportionally affect sales amount, which only dropped by 11.1% year-on-year, nearly 10 percentage points less than the decline in sales volume. The difference was mainly due to the rise in average prices.
The average online market price reached 7,885 yuan, up 12.3% year-on-year. Compared to the 8.2% year-on-year increase in the average price in the first half of this year, the average price has risen to a new level in just two months. This indicates that the online sales structure in August continued to shift towards higher price segments, with mid-to-high-end products gaining more weight in the overall market. On the other hand, it also reflects the persistently high costs of core components such as storage.
Price Segment Analysis: Apple Drives the 4,000-5,999 Yuan Segment, Share of Models Priced Over 10,000 Yuan Surges
In the online market in August, the 4,000-5,999 yuan price segment, driven by Apple's entry-level models, saw its share increase by 8.7 percentage points year-on-year to 28.7%, surpassing the 6,000-7,999 yuan segment.
Meanwhile, the market share of high-end models priced over 10,000 yuan rose to 23.7%, a significant increase of 11.6 percentage points year-on-year. AI flagship models and professional creative notebooks were the core drivers of growth in this price segment.
Correspondingly, the number of budget models priced under 4,000 yuan decreased significantly, with some brands temporarily discontinuing their low-end product lines. The sales share of the 6,000-7,999 yuan segment fell to 17.0%, down 10.6 percentage points year-on-year.
Runto predicts that due to limitations in storage production capacity, the tight supply-demand balance for consumer-grade storage will continue until at least 2027. The upward trend in terminal average prices will remain the main theme of the market in the fourth quarter, with manufacturers more likely to adjust configurations and product tiers to absorb cost pressures.
Brand Performance: Leading Market Structure Remains Stable, Apple and Xiaomi Buck the Trend to Gain Market Share
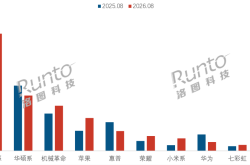
The Lenovo group maintained its leading position in the online market in August with a 34.3% sales share, demonstrating the strongest risk resistance during market fluctuations.
The ASUS group and Mechrevo ranked second and third, respectively. Their differentiated Layout (product positioning) in gaming notebooks and high-performance creative notebooks were the main supports for their market shares.
Apple was the standout brand this month, with its online market sales share increasing by 3.7 percentage points year-on-year to 9.6%, the highest increase among the TOP 10 brands.
Xiaomi, relying on its Redmi product line, saw its share increase by 2 percentage points year-on-year.
Online market shares of brands such as HP, Huawei, and Dell all declined to varying degrees.
Sales Share and Changes of Top Brands in China's Online Notebook Computer Market in August 2026
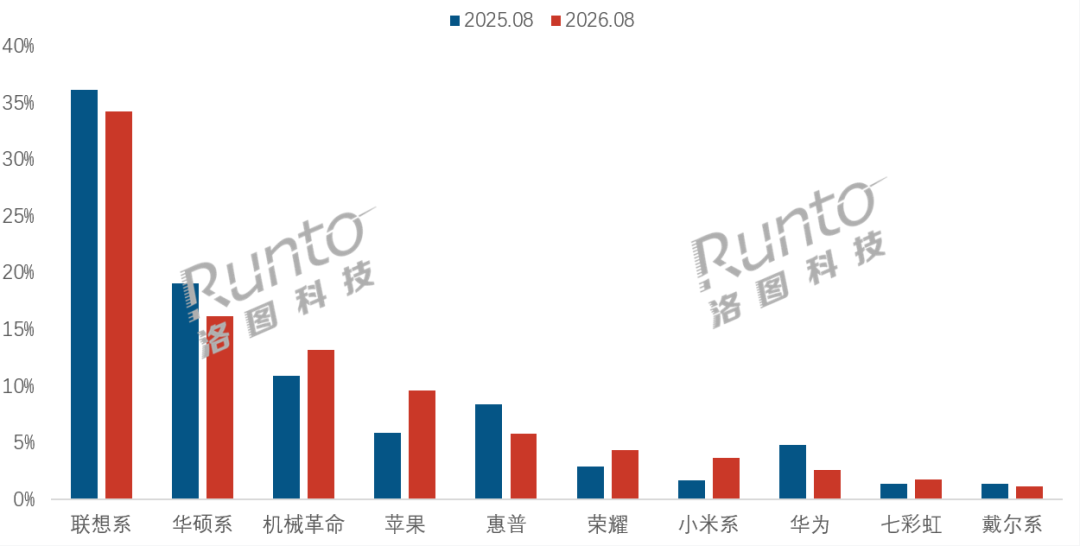
Data Source: Runto Online Monitoring Data, Unit: %
Outlook: Cost Constraints and AI Drivers Reshape the Market Amid Stock Game
Overall, China's online notebook computer market has bid farewell to the era of rapid growth and entered a phase of structural Upgrade amid stock game. The deep integration of AI technology and the self-sufficiency of the supply chain will be the core variables determining the evolution of the industry landscape in the next one to two years.
In the short term, the high costs of core components such as storage and displays will continue to constrain the supply of entry-level models, with significantly narrower room for price reductions during major sales events compared to previous years. On the product side, AIPC will remain a core focus for manufacturers, with brands accelerating the launch of lightweight AI models in the mid-range price segment, seeking a balance between cost constraints and product adoption.
In the medium to long term, market differentiation will further intensify. On one hand, manufacturers with strong supply chain capabilities, multi-device ecosystem synergy, and differentiated product Layout (positioning) will have a better chance of capturing existing users during market contraction. On the other hand, product strategies relying solely on low prices will face sustained pressure, with the contraction of low-end product lines likely to become a long-term industry trend.
Thank you for reading. If you found this insightful, please like, share, and follow.
-
![]()
Changsha Computing Power Firm Lands Another Order Worth Nearly 900 Million Yuan
-
![]()
Jiemei Technology’s Restructuring Plan Greenlit: Set to Acquire Afos Technology for 915 Million RMB
-
![]()
Revenue of 200 Million, Then Another 200 Million Invested! Transight Optoelectronics Takes a Bold Bet on Ultra-Precision Optics Pilot Production
-
![]()
What is the True Value of Zhipu's $3 Billion ARR Amid the 'Data Leak' Controversy?
-
![]()
Monthly Report | China's Online Notebook Computer Market in August 2026: Sales Volume Drops 21%, Apple and Xiaomi Buck the Trend to Gain Market Share; Average Price Rises 12%, Share of Models Priced O
-
【Focus】Low-drag disc brake assembly reduces energy loss and holds great potential in new energy vehicles
-
![]()
Lying Flat in a Car: Is There a 4.4-Fold Increase in the Risk of Severe Injury During a Collision?
-
![]()
Honor Magic9 Pro Max Review: Imaging Gets More Exciting, Agent System Impresses