OpenAI Hits Pause on the AI Race: The Hype Around Large Models Cools Down, and Enterprise AI Enters the Era of Results-Based Adoption
 09/14 2026
 570
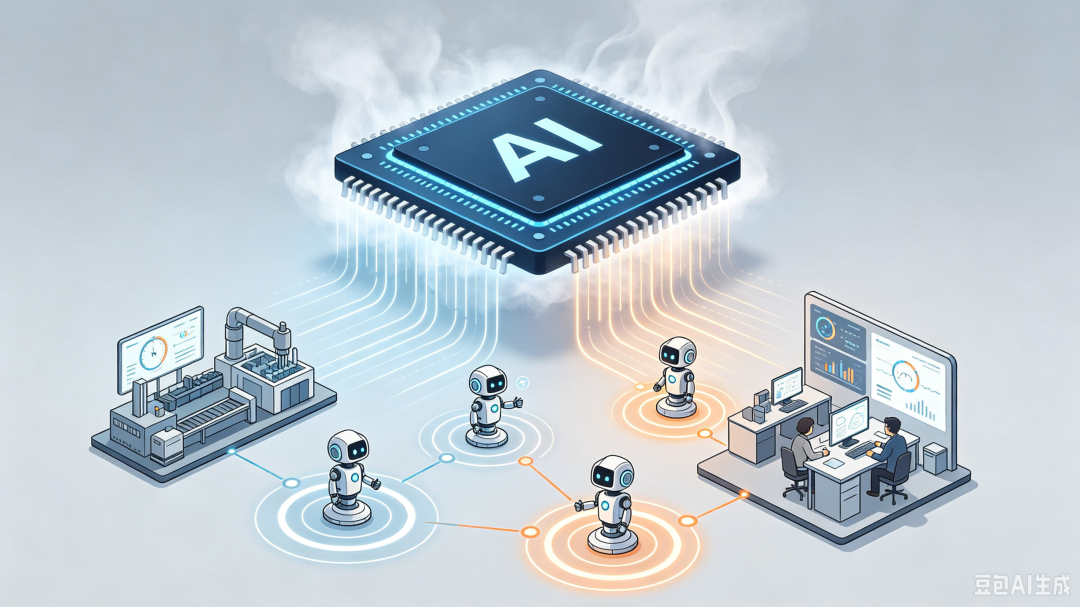
Where Is AI's Next Frontier? /AI Infographic
Manual Labor / Digger Bro
Manually Edited / Uncle Jiao
Produced by / Unicorn Observer
On September 12 (local time), a landmark shift occurred in the global AI landscape: Anthropic publicly called on the industry to voluntarily slow down the pace of iterative development for cutting-edge large models. OpenAI CEO Altman publicly endorsed this stance while explicitly ruling out plans for an IPO in 2026. Leading labs that once raced to scale model parameters and chase AGI narratives are now hitting the brakes on frontier base model competition.
Meanwhile, AI leaders in the secondary market have seen their valuations collectively correct, while domestic primary market funding is gradually moving away from blindly chasing pure large model concepts.
As global capital market enthusiasm for large models rapidly fades, a sharp industry consensus is forming: Over the past two years, a significant portion of enterprise AI projects have remained stuck in the “demonstrable but difficult to validate” phase. Investors and CIOs have grown weary of parameter leaderboards, smooth dialogues, and flashy demos. The yardstick for procurement decisions has fundamentally shifted—no longer asking how powerful the model is, but whether it can reliably deliver quantifiable business results.
On one hand, many enterprise AI projects are trapped in the dilemma of “going live only to be shelved”: After investing millions in private deployment, models score high on evaluations but struggle in real-world business scenarios due to frequent hallucinations and broken processes, making it difficult to link them to business metrics. On the other hand, successful implementations of vertical intelligent agents continue to emerge, with business models like RaaS (Results as a Service) and revenue-sharing taking hold.
The market is undergoing a filtration process: General-purpose large models fuel imagination, while role-based agents deliver productivity. Enterprise AI has officially entered the era of results-based adoption.
01 Procurement Logic Flips Completely
From 2023 to 2024, the core narrative of enterprise AI procurement was “technological sophistication.” CIOs prioritized parameters, benchmark scores like MMLU, and multimodal capabilities, with vendors competing to impress with demos. During this phase, AI functioned more as an innovation experiment for enterprises, with success measured by “completing AI pilots” rather than driving cost reductions or revenue growth.
However, this logic has inherent flaws in real-world business scenarios. General-purpose large models excel at open-ended conversations but struggle with rule-heavy, high-accountability industry environments due to three persistent issues: hallucinations, lack of traceability, and high inference costs. Many vendors rushed projects to market using “generic API + RAG wrapper” approaches, only to see latency fluctuations, uncontrollable responses, and audit failures emerge during peak business volumes. While technical metrics looked impressive, business units refused to sign off.
The industry’s evaluation framework is being rebuilt.
Enterprises are no longer paying for “model capabilities” but for stable, auditable, and measurable business outcomes. According to Gartner research, the primary cause of enterprise AI project failures in recent years has often been the inability to establish credible links between AI outputs and business KPIs. Procurement has shifted from buying software outright to performance-based settlements, anchoring AI’s value to metrics like work order completion rates, quality inspection error rates, customer acquisition conversion, and labor savings.
Divergence is also evident in office scenarios. Microsoft Copilot, DingTalk AI, and Tencent WorkBuddy have entered the fray, while Baidu launched Baidu Dazi, a desktop agent that automates cross-file and cross-software tasks via simple voice commands, transforming AI from text-based dialogue into a hands-on office assistant. The fierce competition among tech giants in AI-powered office tools essentially revolves around capturing efficiency gains in general-purpose scenarios. However, these products primarily address document, reporting, and presentation tasks for individuals and teams, where error tolerance is higher. They are ill-suited for industrial-grade business environments like logistics, finance, and telecommunications, which demand high concurrency, strict service standards, and robust regulation.
This shift is forcing the field to split definitively: One path continues chasing the upper limits of general-purpose foundational models, focusing on broad efficiency improvements. The other path anchors itself in industrial scenarios, packaging agents as 24/7 workforce replacements to address high-frequency, standardized, and quantifiable industry needs.
The concept of “silicon-based employees,” proposed by Bairong Smart CEO Zhang Shaofeng, embodies this trend: AI is no longer a supplementary tool but a silicon-based workforce capable of independently fulfilling complete job roles, integrating into business performance reviews, and aligning with production rhythms. It prioritizes not model generalism but the real operational workflows of specific roles, combining voice interaction, long-context understanding, business decision-making, and compliance logging into an end-to-end execution loop. Built on Baigong AgentOS, these silicon employees are deployed in frontline roles like customer service, operations, and risk control, with RaaS models tied to business metrics—breaking free from traditional model sales and project-based delivery.
Innovation Works Chairman Kai-Fu Lee has repeatedly emphasized in public interviews a similar view: The key to AI-driven productivity transformation lies not in the extreme capabilities of general-purpose models but in delegating massive standardized, repetitive tasks to agents, freeing humans for more creative work.
02 The Agent Field Splits Inside and Out
Overseas Agent startups have explored role-based implementations earlier. Sierra focuses on closing customer service tickets with agents, prioritizing reduced manual intervention over broad capabilities. Harvey targets the legal industry, using agents for contract review and regulatory searches, delivering verifiable document conclusions.
Overseas solutions excel in smooth interactions and mature tool integration but are mostly tailored to lightweight, low-constraint Western business environments. When deployed in domestic industries like logistics, finance, and telecommunications—which demand high concurrency, strict service standards, and full-process traceability—they face inherent stability issues, compliance audit gaps, and localization challenges.
The core barrier to domestic industrial adoption has never been “can it converse” but “can it withstand scaled production.” Scenarios like logistics customer complaints, order inquiries, and exception claims are high-concurrency, long-conversation, and complex, requiring agents to deliver real-time responsiveness, semantic understanding, long-duration dialogue stability, and full-chain traceability. Generic wrapper models frequently suffer from response breaks, semantic drift, and latency spikes, failing to meet routine production demands.
In large-scale deployments at leading logistics firms, Bairong Smart’s “Silicon-Based Customer Service” provides a blueprint for vertical role-based agents. After going live, the agent underwent complete production validation across ramp-up, peak pressure, and scenario iteration phases. From handling fewer than 1,000 calls daily at launch in July, it steadily scaled to over 15,000 daily calls while supporting ultra-long continuous dialogues—perfectly aligning with logistics’ complex inquiries and multi-issue communication needs. This thoroughly validated the stability and usability of vertical role-based agents in high-concurrency real-world production.
This logistics case precisely reflects the core logic of domestic enterprise Agent adoption: Industrial-grade agents must embed industry operational standards, service norms, and scenario pain points into decision-making and interaction workflows, refined through real business peak loads rather than laboratory demo metrics.
This explains why vertical track (vertical track is translated as “vertical track” here, but if it refers to a specific term like “vertical sector,” adjust accordingly) vendors insist on self-developed vertical foundations and deep scenario operations—the scaled deployment thresholds in logistics, finance, and telecommunications are insurmountable for generic API wrappers or lightweight RAG modifications. Peak concurrency stability, long-conversation accuracy, and full-chain traceability are the true benchmarks for industrial AI validation.
Of course, this vertical adoption path involves clear trade-offs. Role-based agents, deeply tied to industry-specific workflows and service rules, require prolonged scenario refinement, data iteration, and business alignment, expanding far slower than the lightweight replication models of general-purpose models and office agents.
A silicon-based customer service agent refined for logistics still needs targeted reconstruction for other industries—a heavy-engineering, heavy-operation, slow-iteration, high-barrier long-term track (track) rather than a short-term traffic play.
03 The Bottleneck Lies in Organization
Many attribute enterprise AI adoption challenges to insufficiently powerful models, but real pain points in industrial settings stem more from organizational barriers. Delivering AI-driven business results is not just a technical issue but requires restructuring human-machine accountability, job workflows, and performance metrics.
When silicon-based employees enter business processes, enterprises must answer new questions: Which AI preliminary judgments require manual review? How are AI errors attributed? How should existing team KPIs adjust to accommodate human-AI collaboration? Many AI projects succeed technically but fail organizationally because businesses resist changes, roles blur, and agents cannot truly integrate into production workflows.
The technology cost curve has improved markedly: Compared to 2023, large model inference costs have plummeted, and modular agent development frameworks are now widespread, significantly lowering the engineering barriers for enterprises to build agents. Platforms like AWS Bedrock, Baidu GenFlow, and Baigong AgentOS are reducing development costs for agent orchestration. Compute supply and model toolchains are no longer the primary bottlenecks; quantifying business metrics, defining human-machine accountability, and enabling full-chain auditable trust are now the core challenges for scalable enterprise AI adoption.
Capital preferences have shifted accordingly. Funding once chased model parameters and foundational model teams; now, investments in the Agent track prioritize quantifiable adoption cases, sustained operational capabilities, and viable business models. Deloitte’s 2026 Enterprise AI Survey reveals that while about two-thirds of companies with scaled AI deployments report efficiency and cost improvements, only a limited share achieve revenue growth. Meanwhile, Agent projects stuck in demos without business metric closed loop (closed loops) are rapidly losing patience from capital and clients.
The technological dividends of large models have not vanished—the hype phase has simply passed. Just as OpenAI and Anthropic are recalibrating the pace of frontier model competition, domestic industrial AI is moving beyond conceptual hype into a more pragmatic validation era.
General-purpose large models will continue pushing the boundaries of intelligence, while tech giants’ AI-powered office agents address efficiency gains in general workplace scenarios. The deep fulfillment of enterprise productivity, however, will rely more on role-based vertical agents. Overseas players like Sierra and Harvey, along with domestic vendors deep cultivation (deeply rooted) in logistics, finance, and telecommunications, all converge on the same judgment: When enterprises procure AI, they ultimately buy not models but stable, role-based business results.
In the coming years, what will determine the survival of enterprise AI vendors is no longer flashy demo launches but a complete capability set: understanding role-specific tasks, integrating with business systems, meeting industry standards, quantifying business gains, and sustaining iterative operations. After the bubble bursts, role-based agents capable of delivering results will become the infrastructure of enterprise digitalization.
The cooling of large model hype does not signal the end of AI’s rise but marks a new beginning where AI truly becomes foundational infrastructure for societal productivity. (End)
-
![]()
Rescuing Neta Auto: Even Taiyi Zhenren Steps In, and Associated Company’s Value Soars by 2.5 Billion Yuan
-
Why Does 'Taiyi Shenglian' Step In to Save Neta?
-
![]()
Registered Capital Sees Slight Reduction to 110.7291 Million Yuan! Yongxin Optics Finalizes Industrial and Commercial Registration Amendments
-
![]()
Renaming Marks the Start: Conant Optics’ Smart Glasses Business Gets a Full-Throttle Boost
-
Amazon’s Shift to Passkey Compels Home Furnishing Brands to Overhaul Backend Access Controls
-
![]()
Doubao Mobile Phones: Opting for the Path of Maximum Public Discourse
-
![]()
OpenAI Hits Pause on the AI Race: The Hype Around Large Models Cools Down, and Enterprise AI Enters the Era of Results-Based Adoption
-
![]()
Li Feifei's Atlas Opens the Door to a New World for Embodied AI