Dong Mingzhu Blames Gree's Profit Decline on Copper Prices: A Fact, But Not the Whole Story
 11/11 2026
 485
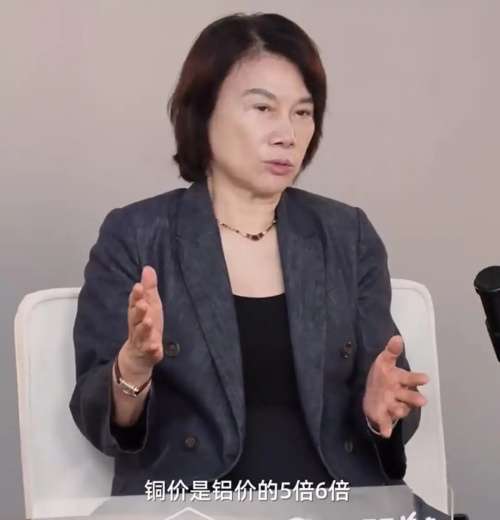
"When our financial results came out this year, everyone said the same thing—Gree's decline has been severe, and that's true. So what's the reason? It's because the price of our copper is rising." Recently, Gree Electric Chairman Dong Mingzhu addressed the reasons behind the company's performance decline this year during an appearance on Tmall's Double 11 "Life Proposal Bureau" program.
Dong noted that copper costs five to six times as much as aluminum, and Gree insists on using copper materials to ensure product quality. As for substituting aluminum for copper, she was blunt: "Can you do it? Of course you can, but its stability, reliability, and durability all have to be called into question."
"I would rather lose several billion in profit than compromise product quality," Dong emphasized. In my view, her statement reflects an objective fact—but not the whole truth. A more accurate assessment is this: rising copper prices did indeed squeeze gross margin, and Gree's insistence on holding prices steady and refusing to swap copper for aluminum has kept more cost pressure in-house. But weakening industry demand, channel reform, and reduced economies of scale are also weighing on profits.
In the first three quarters of this year, the average domestic copper price was about 103,800 yuan per ton, up 32.6% year on year, while the average aluminum price was about 24,000 yuan per ton, up 17.4% year on year. Given that copper accounts for roughly 20%–30% of the cost of an air conditioning unit, rising copper prices may have added 200–300 yuan to the cost per unit. That is why Gree's single-quarter gross margin fell from 28.31% in the same period last year to 22.69% in Q3 this year—a drop of 5.62 percentage points.
At the same time, Q3 revenue came in at 36.678 billion yuan, down 7.97% year on year, and net profit was 3.996 billion yuan, down 43.31% year on year. The decline in net profit was significantly larger than the decline in revenue, which shows that raw material costs are indeed an important variable—in other words, rising copper prices are real pressure.
That said, Gree's profit decline cannot be attributed to copper alone. Whether it is the 43.31% year-on-year drop in Q3 net profit or the 19.51% decline in net profit for the first three quarters, copper prices are not the only culprit. At least three other factors are at play:
① Weakening industry demand: In the first three quarters, total sales in the household air conditioning industry reached 150 million units, down 8.4% year on year. The decline widened to 15.1% in Q3, far higher than the 2.8% in Q1 and 9.3% in Q2.
② Hindered price transmission: Gree insists on competing on quality rather than price, and its selling prices have remained relatively stable. Early in the year, it publicly promised not to raise prices on household air conditioners, which prevents it from fully passing costs on to consumers.
③ Reduced economies of scale: As revenue declined, the ability to spread fixed expenses weakened, and channel reform also affected cash collection and operating leverage.
Dong's statement is both an explanation and a brand strategy. By framing the profit decline as "rather lose several billion than lower quality," she is essentially crafting a brand narrative—turning operating pressure into differentiation propaganda for long-termism and genuine copper materials. For consumers, this does mean more stable materials and no price increases in the short term. For investors, however, the key question is whether this strategy can translate into a higher brand premium and market share gains.
In other words, the capital market is more focused on subsequent verification. Any observant person can see that Dong's public remarks put Gree's trade-offs directly on the table: she acknowledges the damage of the cycle while actively shaping the refusal to cut specifications into a brand moat. But the market also draws a clear distinction—brand favorability does not equal profit. It is still watching several important signals:
Whether copper prices fall back, whether Gree can repair gross margin through price increases or product mix improvement, whether channel reform stabilizes, and whether high-end new products can support a premium. If copper prices retreat later, Gree will see gross margin recovery; but if demand remains sluggish, the sales bottleneck will persist even if copper prices decline.
In addition, if Gree's Q4 gross margin fails to rebound significantly, it would show that cost pressure has not yet been fully digested. If market share continues to rise and premiumization delivers, this narrative of sacrificing profit to protect quality will be more readily accepted by the market. Let the dust settle for a while, and time will give the answer.
-
XFusion Set for Listing Review: A Bet on Computing Power in the Agent Era and a Growth Model for Domestic Computing Power Breakthroughs
-
![]()
StepFun Refuses to Be Just a Cloud-Side Water Seller
-
![]()
Another Computing Power Company IPOs: 70% of Revenue from ByteDance, with Oracle Close Behind
-
![]()
Who Is Squeezing Crystal Optech's Profits as Exclusive Supplier to a Major North American Customer?
-
![]()
Zhongrun Optics Finalizes New Management Team with Completed Board Reshuffle
-
![]()
Between the Pupil Function and the MTF Lies a Fourier Transform
-
Apple, Huawei, and Xiaomi Sales Over the Past 8 Years: Who Really Took Away Huawei's Users?
-
![]()
Huawei Starlight Phone Faces Uncertainty Even Before Launch: Stores Say No Notice Yet, and It Won't Come Cheap