Xingyu Shares Cancels Contracts of 107 New Graduates—Not for Listing, but for a Far Grimmer Reason
 09/14 2026
 353
Xingyu Shares has recently found itself at the center of a public outcry.
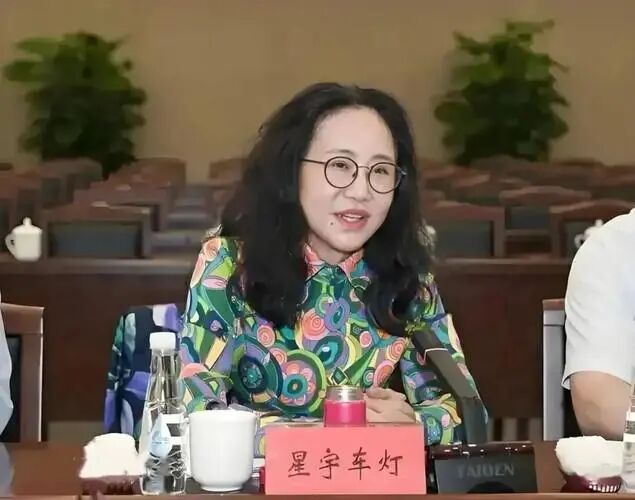
This Changzhou-based company, renowned as the "King of Automotive Lighting," submitted its prospectus to the Hong Kong Stock Exchange in July, aiming for a dual A+H listing. Around the same time, it came to light that the company had collectively terminated the employment contracts of 107 new graduates.
When these two events coincided, the initial online speculation was that the company, in an attempt to polish its prospectus, had initially hired individuals to inflate its R&D staff numbers, only to lay them off after submitting the listing documents.
This narrative gained traction, but a closer examination of the timeline and data reveals its fragility. The truth, in fact, is far more troubling than mere prospectus embellishment.
1
Prospectus Data Bears No Relation to These Graduates
The prospectus was submitted in July, yet the financial data it contained only extended up to March 2026, i.e., the first quarter report.
This means that all operational figures in the prospectus were frozen as of March 31, 2026. The 107 new graduates, however, were hired in July and had their contracts terminated in August. They never appeared in any of the prospectus' financial statements. The number of hires did not influence the proportion of R&D personnel, nor could the terminations alter the already submitted documents. The recruitment and subsequent layoffs of these individuals had no impact on the prospectus.
Now, let's delve into the job structure. Among the 107 individuals whose contracts were terminated, 60 were in production and manufacturing, 39 in R&D, and 8 in administrative roles.
If the motive had truly been to inflate R&D personnel numbers, all hires should have been in R&D positions. In reality, two-thirds were in production and manufacturing.
These individuals were part of a large-scale campus recruitment initiative aimed at grooming reserve talent. Initially hired en masse, they were later assigned to workshops, laboratories, and offices as needed. The notion of embellishing R&D data falls apart when scrutinized against the job distribution.
Having dismissed this explanation, only one question remains: Why did the company hire and then lay off these individuals?
2
A Year's Time: The Company's Business Takes a Downturn
The answer lies in the rapid deterioration of the company's performance.
In 2025, Xingyu Shares reported revenue of 15.257 billion yuan, up 15.12% year-on-year, with a 70.2% market share in the domestic smart automotive lighting market. These figures exuded confidence and expansionary ambition.
Based on this performance, hiring 440 high-caliber new graduates in 2026 was a logical step.
With orders secured and capacity expansion underway, both production lines and laboratories required additional manpower. Hiring and retaining these individuals was a bet on continued growth.
The issue arose because these students were recruited during last year's autumn and this year's spring recruitment drives, primarily the previous year. From interview to onboarding, over half a year elapsed. By the time these 440 individuals arrived at the factory gates in July, Xingyu's business conditions had taken a turn for the worse.
In the first half of 2026, the company's revenue was 6.884 billion yuan, up just 1.87%, with the second quarter turning negative; net profit attributable to shareholders fell 18.26% year-on-year. The gross profit margin slid from 20.58% in 2023 to 18.76% in the first half of 2026, marking three consecutive years of decline.
In terms of customer structure, Customer A in the prospectus, formerly the largest client, saw its contribution drop from 3.752 billion yuan in 2023 to 2.971 billion yuan in 2025, with its share shrinking from 36.6% to 19.5%, further falling to 16.2% in the first quarter of 2026. The largest client nearly halved in three years.
Individuals hired last year for capacity expansion now faced a shrinking reality.
Last year's planned capacity went unused, and reserve talent had no positions to reserve. Thus, among the 440 hires, 107 had their contracts terminated.
Performance declined, unable to sustain expansionary ambitions, so people were laid off. The logic is harsh but the chain is complete.
3
The Coldest Calculation: The Precise Accounting
What truly mars this incident is the company's meticulous calculation of legal compensation.
These new graduates had only been on the job for a month, less than six months. According to the Labor Contract Law, the statutory compensation for mutually agreed termination is half a month's salary.
The company offered half a month's salary, roughly 5,000 yuan each, to those who voluntarily agreed to leave.
Note a detail: voluntary resignation legally requires no compensation at all. This half-month's salary was to secure their signatures.
The alternative was forced layoffs. If deemed unlawful termination, the compensation would be 2N, i.e., one month's salary, roughly 10,000 yuan each.
The difference between the two paths was about 5,000 yuan per person. For all 107 individuals, the legal risk exposure was around one million yuan.
The comprehensive cost of retaining these individuals for a year was 18 million yuan.
The cost of harshness was one-seventeenth of decency.
In other words, Xingyu Shares did the math and found harshness cheaper. The 16-plus million yuan saved would be a neat decimal point on the profit margin report.
As for these 107 individuals, they lost far more than half a month's or a month's salary. They missed the entire autumn and spring recruitment window, left with a resume tainted by a one-month employment stint followed by termination, and joined the ranks of the unemployed with their belongings in tow.
For these young graduates just stepping out of campus, this was a heavy blow at the start of their careers, and the cost of this blow was merely 5,000 yuan per person in the company's books.
4
Calculating Compensation, But Losing Public Sentiment
In the wave of electrification and intelligence in the automotive lighting industry, Xingyu Shares has secured the largest market share, with a 70.2% domestic market share—a moat built on decades of technological accumulation. Given its past success, the company's decision to stockpile talent in 2025 based on growth logic was not inherently flawed.
What was flawed was the handling after the downturn.
The decline in performance is explainable; plans cannot keep up with changes, a common occurrence in the business world. The automotive industry has witnessed relentless price wars penetrating deep into the supply chain, with OEMs' annual cost-cutting pressures cascading down to parts suppliers, squeezing gross profit margins industry-wide. Xingyu is not alone in this. During downturns, companies everywhere shrink hiring and freeze headcounts, and the public understands the ebb and flow of business.
But between shrinking and betrayal lies a bottom line. Faced with the young people it had hired, the company chose the path of lowest cost and coldest demeanor.
Using half a month's salary to buy signatures, compressing legal risk to one million yuan, and pricing decency at one-seventeenth.
In the short term, Xingyu won the calculation. The saved money is tangible, and the terminated new graduates are unlikely to pursue lengthy arbitration, with mass litigation unlikely to form quickly.
From a financial perspective, this was a textbook example of cost control.
The long-term account has just begun. A company rushing for a Hong Kong IPO, terminating new graduate contracts in bulk the same month it submits its prospectus, is itself the best annotation to the prospectus.
Investors read the prospectus for risk factors, such as the disclosure of declining customer concentration.
However, the public sees the company through the image of 107 individuals leaving Changzhou with their belongings.
-END-
-
![]()
Rescuing Neta Auto: Even Taiyi Zhenren Steps In, and Associated Company’s Value Soars by 2.5 Billion Yuan
-
Why Does 'Taiyi Shenglian' Step In to Save Neta?
-
![]()
Registered Capital Sees Slight Reduction to 110.7291 Million Yuan! Yongxin Optics Finalizes Industrial and Commercial Registration Amendments
-
![]()
Renaming Marks the Start: Conant Optics’ Smart Glasses Business Gets a Full-Throttle Boost
-
Amazon’s Shift to Passkey Compels Home Furnishing Brands to Overhaul Backend Access Controls
-
![]()
Doubao Mobile Phones: Opting for the Path of Maximum Public Discourse
-
![]()
OpenAI Hits Pause on the AI Race: The Hype Around Large Models Cools Down, and Enterprise AI Enters the Era of Results-Based Adoption
-
![]()
Li Feifei's Atlas Opens the Door to a New World for Embodied AI