Automotive Parts Behemoth Huayu Reports 45.5 Billion Yuan in Q3 Revenue, Net Profit Dips 6.4% to 1.687 Billion Yuan, Yet Stays Robust
 10/29 2026
 535
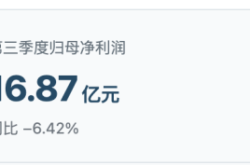
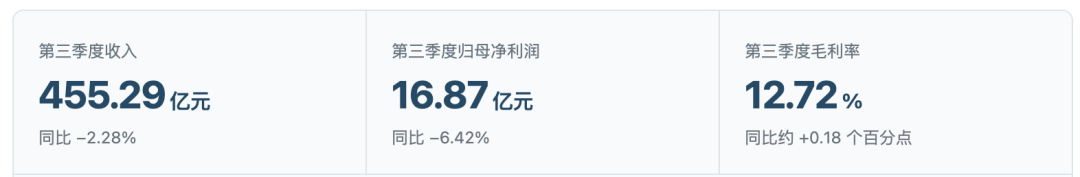
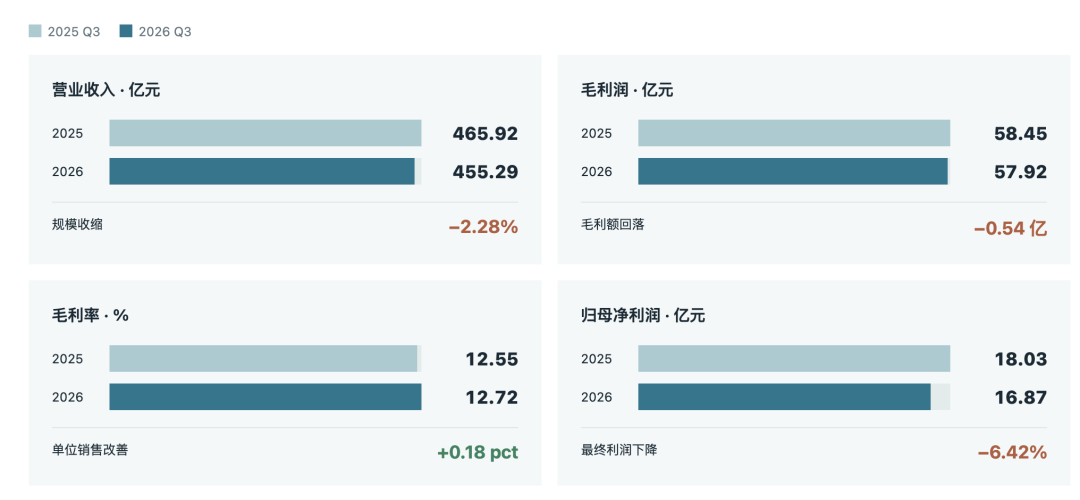
In the third quarter of 2026, Huayu Automotive achieved component sales worth 45.529 billion yuan, marking a 2.28% year-on-year decrease in revenue. The net profit attributable to shareholders stood at 1.687 billion yuan, reflecting a 6.42% year-on-year decline.
Based on quarterly revenue and operating costs, the gross profit margin hovered around 12.72%, showing an uptick of approximately 0.18 percentage points. Nevertheless, the total gross profit saw a reduction from roughly 5.845 billion yuan to 5.792 billion yuan.
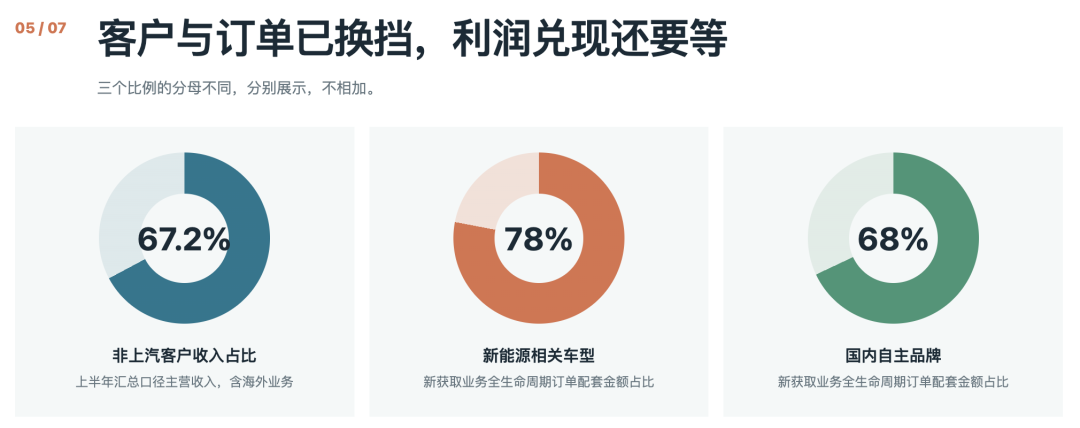
Huayu's customer base, inclusive of its overseas operations, reveals that revenue from vehicle customers outside SAIC Motor constitutes 67.2% of its core business. Prominent clients encompass Tesla Shanghai, Seres, Xiaomi, Geely, BYD, Chery, Li Auto, and XPENG.
In terms of newly secured business orders for the full lifecycle during the same period, new energy vehicle models made up 78% of the matching (supporting) amount, while domestic independent brands accounted for 68%. This trend exhibits remarkable stability!
Part 1: Gross Profit on the Rise, But Where Has the Profit Gone?
First Three Quarters:
◎ Operating revenue: 129.468 billion yuan, a 1.73% year-on-year decrease;
◎ Net profit attributable to shareholders: 4.334 billion yuan, down 7.81%;
◎ Net profit attributable to shareholders excluding non-recurring items: 3.805 billion yuan, a 10.83% decline.
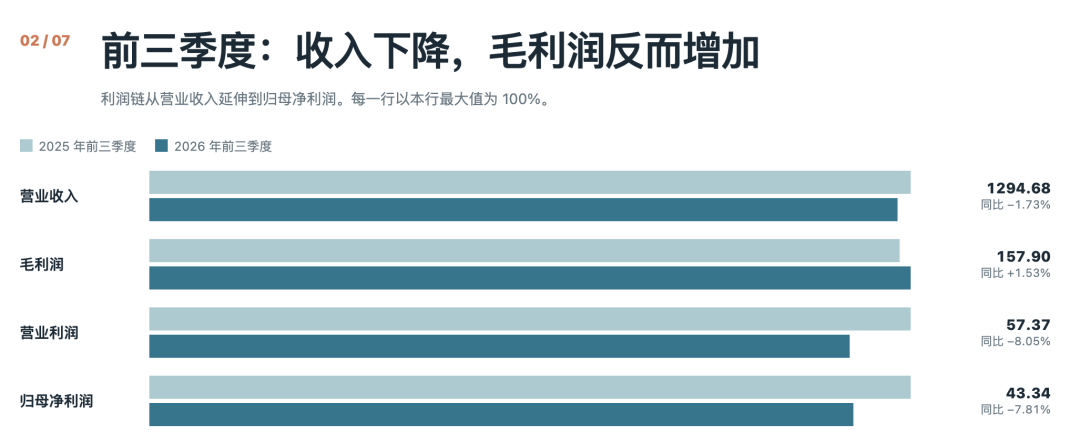
◎ The gross profit margin climbed from roughly 11.80% in the same period last year to 12.20%, with gross profit increasing by about 237 million yuan.
◎ Operating profit for the first three quarters dwindled from approximately 6.239 billion yuan to 5.737 billion yuan.
Breaking down the disparity:
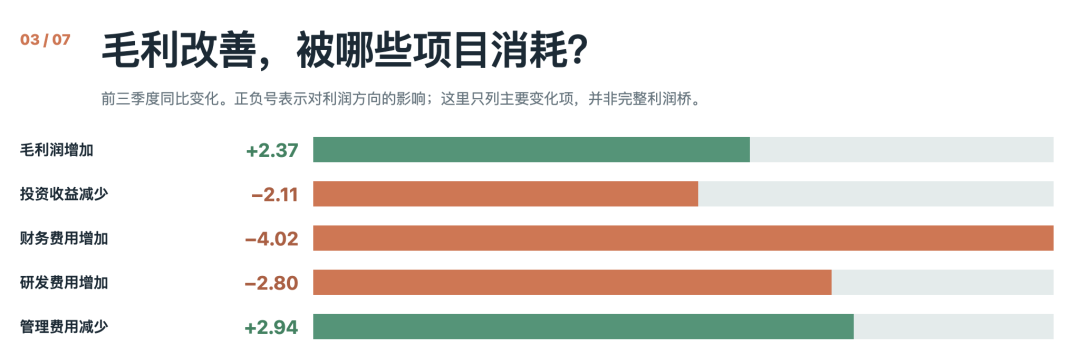
◎ Investment income diminished by roughly 211 million yuan year-on-year, including a decrease of about 328 million yuan in investment income from associated and joint ventures;
◎ R&D expenses surged by approximately 280 million yuan;
◎ Financial expenses rose by about 402 million yuan; administrative expenses decreased by roughly 294 million yuan, mitigating some of the pressure.
The uptick in financial expenses in the semi-annual report was primarily linked to exchange losses stemming from currency fluctuations.
Focusing solely on the third quarter:
◎ Gross profit decreased by approximately 54 million yuan year-on-year;
◎ Investment income dropped by about 164 million yuan;
◎ R&D expenses increased by roughly 141 million yuan.
The company managed to reduce administrative expenses but still couldn't avert the decline in operating profit. While gross profit persists, achieving equilibrium between the scale of traditional business, equity participation returns, and transformation investments will require time.
Part 2: Why Hasn't the Profit Structure Aligned with Order Shifts?
In the current fiercely competitive automotive market, suppliers secure more platforms, yet profitability per platform remains challenging to gauge.
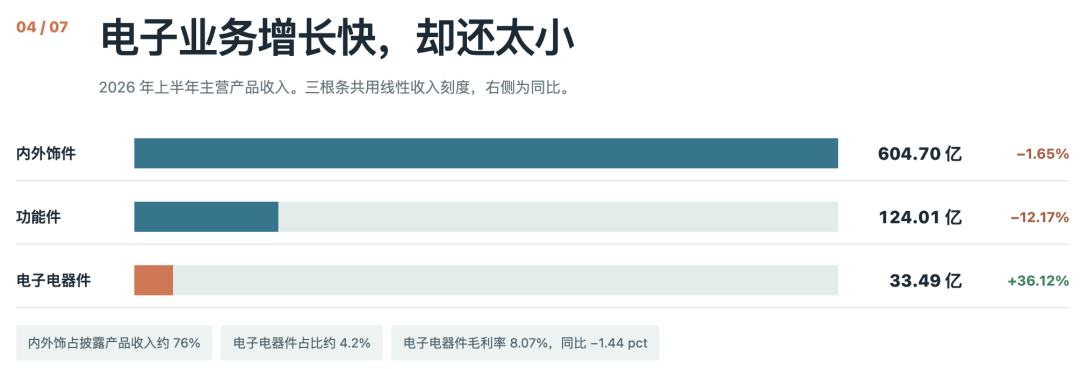
◎ First-half revenue from interior and exterior trim components: 60.470 billion yuan, constituting approximately 76% of main business product revenue, a 1.65% year-on-year decrease;
◎ Revenue from functional components: 12.401 billion yuan, a 12.17% decline.
◎ Revenue from electronic and electrical components: 3.349 billion yuan, a 36.12% increase, accounting for only approximately 4.2%, with a gross profit margin of 8.07%, a 1.44 percentage point year-on-year decrease.
Although the electronic business is experiencing rapid growth, its scale and profitability are not yet adequate to bolster the group.
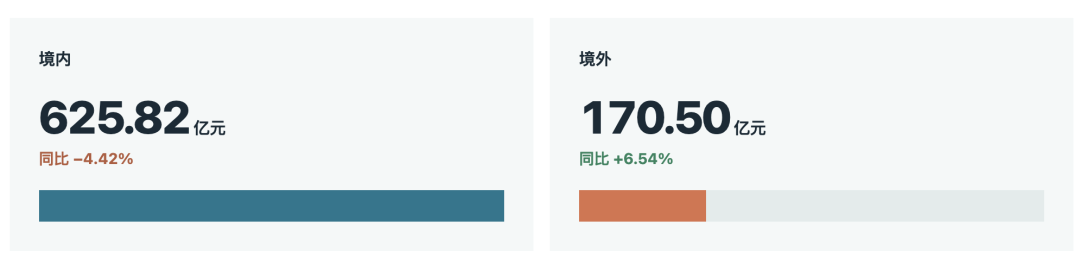
◎ First-half overseas main business revenue: 17.050 billion yuan, a 6.54% year-on-year increase;
◎ Domestic revenue: 62.582 billion yuan, a 4.42% year-on-year decrease. Overseas growth provides a cushion.
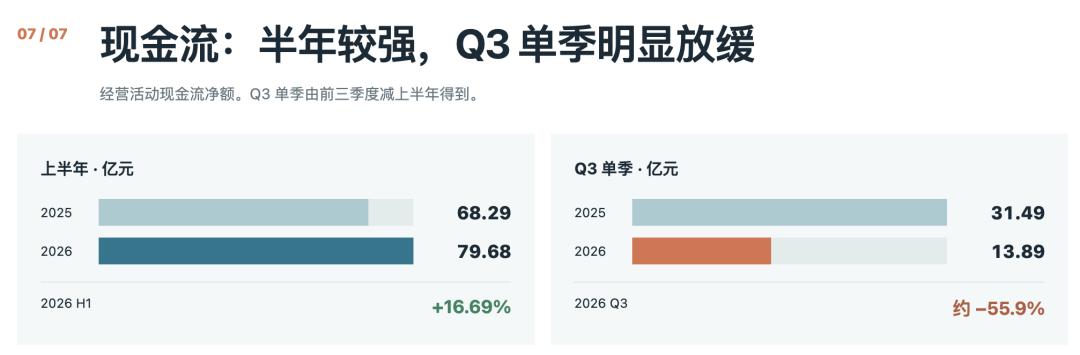
Net operating cash flow for the first three quarters reached 9.357 billion yuan, significantly surpassing the net profit attributable to shareholders of 4.334 billion yuan for the same period, indicating an overall decent recovery.
However, first-half operating cash flow stood at 7.968 billion yuan, a 16.69% year-on-year increase. By deduction, the third quarter witnessed approximately 1.389 billion yuan in inflows, compared to approximately 3.149 billion yuan in the same period last year (restated).
Huayu continues to bolster its intelligent chassis capabilities this year. In October, it was revealed that subsidiary Shanghai Huizhong plans to publicly acquire a minority stake in Unitron Auto Electronics.
Summary
Huayu's Q3 2026 financial report is generally commendable. In comparison to SAIC Motor's joint venture system, its automotive components business remains resilient.
-
![]()
Fuyao Glass Reports 14.97% Drop in Net Profit to 6.006 Billion Yuan for First Three Quarters, While Dimming Glass Yield Soars from 10% to 90%
-
![]()
GPS is Vulnerable to Interference, This Startup Aims to Provide a Centimeter-Level Alternative with 258 Satellites
-
![]()
Desay SV’s Q3 Revenue Hits 9.519 Billion Yuan, Up 23.75%; Overseas Gross Margin at 31.34%, Domestic at 17.58%
-
![]()
Automotive Parts Behemoth Huayu Reports 45.5 Billion Yuan in Q3 Revenue, Net Profit Dips 6.4% to 1.687 Billion Yuan, Yet Stays Robust
-
![]()
Li Auto Shifts Focus: Can Chips, Batteries, and L4 Tech Drive the Next Phase of Competition?
-
Suzhou: Not Just Aiming for Daily Access to Driverless Cars, but Transforming the Entire City into a 'Testing Ground' for Embodied AI
-
![]()
Who Benefits More from the Split of FAW-Audi and SAIC-Audi?
-
40-Year Reversal in Technology Flow: Why Did Volkswagen Transform China from a Factory into a Global Development Hub?